You and your siblings just inherited a house. Emotions are high, the mailbox is filling up, and the clock may be ticking on insurance, taxes, or a mortgage.
Before anything else, decide who has legal authority to act and what outcome would feel fair enough to accept. With that set, the rest becomes a series of clear, doable steps.
Confirm who can legally sign and when
Figure out whether the estate must go through probate. In many states, a will must be admitted to court and someone appointed as personal representative before a sale can close. Ask a probate attorney about what applies in your state and whether a small estate process might be available.
Gather proof of authority. This often means certified death certificates, the will, and court-issued letters naming the executor or administrator. If there is a transfer-on-death deed or a living trust, get those documents too because they may allow a quicker transfer.
Agree in writing on goals, timing, and a point person
Have a short meeting and put the basics in writing. Decide the acceptable time window to sell, a realistic minimum net everyone could live with, and whether anyone wants to buy out the others. Set a communication rule, for example weekly updates by email with decisions confirmed in writing.
Name a single point of contact for agents, buyers, attorneys, and vendors. This avoids crossed wires and mixed instructions. If you struggle to agree, consider a mediator or the estate attorney to help settle process rules without rehashing old conflicts.
Plan access and clean-out without losing valuables
Secure the property to protect estate assets. Confirm insurance is set for a vacant home, keep essential utilities on, and change locks if you lawfully can. Document the condition with photos and a quick video walkthrough.
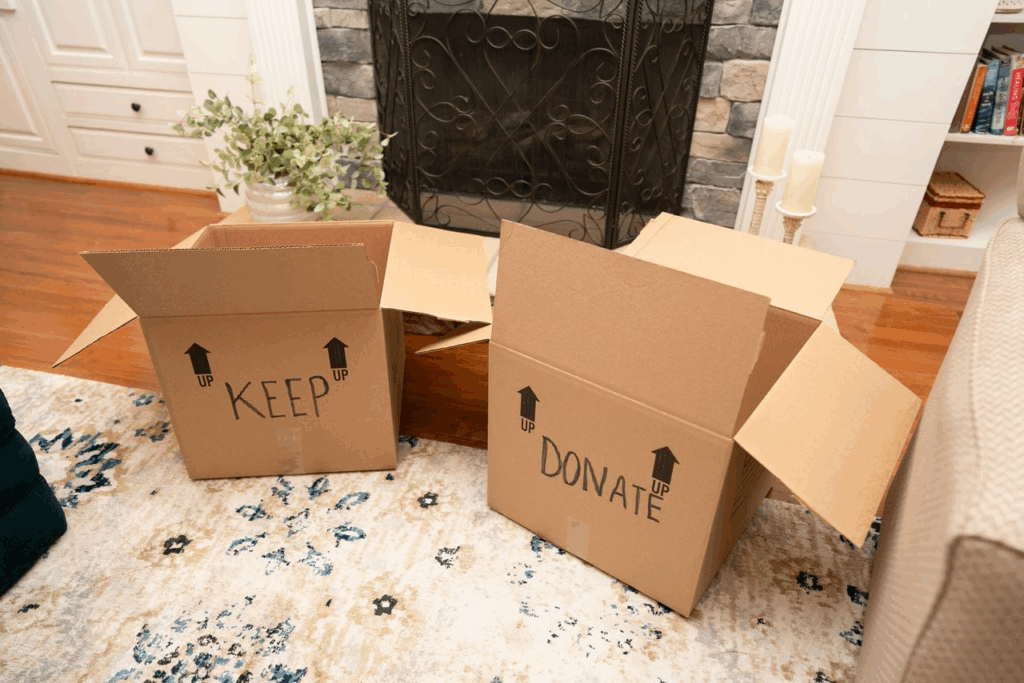
Sort personal property before any repairs or showings. Make an inventory of items each sibling wants, then decide what is sold, donated, or discarded. For larger volumes, interview two estate sale companies and compare fees and timelines. Keep receipts so costs can be reimbursed from closing.
Make the money math visible to everyone
Create a simple net sheet everyone can see. List the likely sale price range, mortgage payoff, property taxes, HOA dues, utilities, insurance, probate or legal fees, possible liens, and estimated closing costs. Update it as real quotes arrive, not guesses.
Decide upfront how costs will be handled. If one sibling fronts expenses, track them in a shared spreadsheet with invoices so reimbursement is simple at closing. If repairs are considered, get two written bids and compare them to an as-is price to see which path actually nets more in the time you have.
Choose a sale path that fits your condition and deadline
Listing with an agent typically nets the most when the home is clean, safe, and you have time. Expect showings, a buyer’s inspection, and 30 to 60 days to close once under contract. Light repairs and staging may improve offers but require cash and coordination.
Selling as-is directly to a home-buying company can make sense when the property needs major work, you face a deadline, or probate is nearly complete and you want one certain date. Request proof of funds, a short inspection window, and a clear addendum about who pays which costs. A company like OC Acquisitions can often accommodate unique timelines and take the property as-is, but compare net numbers to your other options.
Other paths include a sibling buyout using a refinance, holding as a rental if one person will actively manage, or a short-term loan to finish probate and then list. A buyout can keep the property in the family but needs an appraisal and loan approval. Renting may work if cash flow is real after taxes, insurance, repairs, and management, and everyone is comfortable being co-owners for the long haul.
What to handle this week to keep the sale moving
- Order 5 to 10 certified death certificates and locate the will, trust, and deed.
- Call a probate or real estate attorney to confirm who can sign and whether probate is required.
- Appoint a family point person and write down the target sale window and a net number you could accept.
- Set insurance for a vacant home, keep water and electricity on, and document the property with photos.
- Create a shared net sheet and request written payoffs for the mortgage, taxes, and any liens.
- Schedule two clean-out or estate sale bids and decide a start date for sorting personal items.
- Get two agent opinions and one as-is offer so you can compare timelines and likely net proceeds.
Common questions
Can we sell the inherited house before probate is finished?
In many states, you cannot transfer title until a court appoints a personal representative. Some courts allow a sale during probate if the representative is authorized and follows required notice or confirmation steps. Ask your probate attorney what is allowed in your state.
What if one sibling refuses to sell the house?
Start with a written proposal that shows timing and net proceeds, plus options like a buyout. If agreement is not possible, the personal representative may ask the court for instructions, and in some states a partition action may be an option. Mediation often costs less and preserves more value than litigating.
How do we split proceeds if one sibling paid expenses?
Keep receipts and track payments in a shared log. At closing, the settlement statement can show reimbursements to the paying sibling before the remaining net is divided as the will or state law requires. Get your attorney and the title company to review the documentation early.
This article is general information, not legal, tax, or financial advice. Rules and timelines vary by state and by situation, so confirm specifics with a qualified professional before you act.